Understand Regulations
Stay updated with UAE Corporate Tax laws and requirements.
VAT Advisory Services
Navigate UAE VAT regulations with confidence. Bright Accountant provides comprehensive VAT advisory services in Dubai, helping businesses manage VAT registration, returns, compliance, audits, and tax-related requirements efficiently.
In the UAE corporate tax framework, a “taxable person” refers to any entity required to register, submit tax returns, and, if applicable, pay corporate tax. These include:
UAE-Sourced Income: When a non-resident company operates a physical permanent establishment (PE) in the UAE, the profits derived from that PE are treated as UAE-sourced income. The rules for determining tax liability depend on the nature of the income and any relevant Double Taxation Agreements (DTAs).
Businesses are required to submit corporate tax returns to the government, usually on an annual basis. The tax return determines the company’s taxable income by subtracting eligible deductions and allowances from the total income. This taxable income is then multiplied by the applicable corporate tax rate to calculate the tax payable.
The implementation of corporate tax in the UAE is expected to have a significant impact on the business landscape. It is projected to attract foreign investment, strengthen the UAE’s global competitiveness, and support economic diversification.
Companies that effectively adapt to the new corporate tax system and take advantage of its opportunities will be well-positioned to succeed in the UAE’s evolving business environment.
| Overview
The UAE has introduced a Federal Corporate Tax (CT) to further strengthen its position as a leading global business hub. The tax is designed to support sustainable economic growth while maintaining the UAE's competitiveness and attractive business environment.
At BCA, we provide end-to-end corporate tax services to help businesses understand their obligations, assess their tax position, ensure compliance and plan effectively for the future.
Stay updated with UAE Corporate Tax laws and requirements.
Meet your filing and reporting obligations accurately and on time.
Identify legitimate opportunities for tax efficiency.
Get continuous guidance as your business grows.
Get professional accounting and bookkeeping support tailored to your business requirements.
Taxable income for companies in the UAE refers to the net profit that is subject to corporate tax. The following are generally included in taxable income:
Business Profits: This is the primary component of taxable income and includes revenue from the company’s main operations after deducting related expenses.
Capital Gains: Earnings from the sale of assets such as property or investments are typically considered taxable income.
Calculating Taxable Income:
1.Start with Gross Revenue:This includes all income from your business activities, such as sales, commissions, and fees.
2.Start with Gross Revenue:This includes all income from your business activities, such as sales, commissions, and fees.
3.Determine Profit or Loss: If it’s a profit, that amount is your taxable income. If it’s a loss, it may be carried forward to offset future profits and reduce tax liability (as per applicable rules).
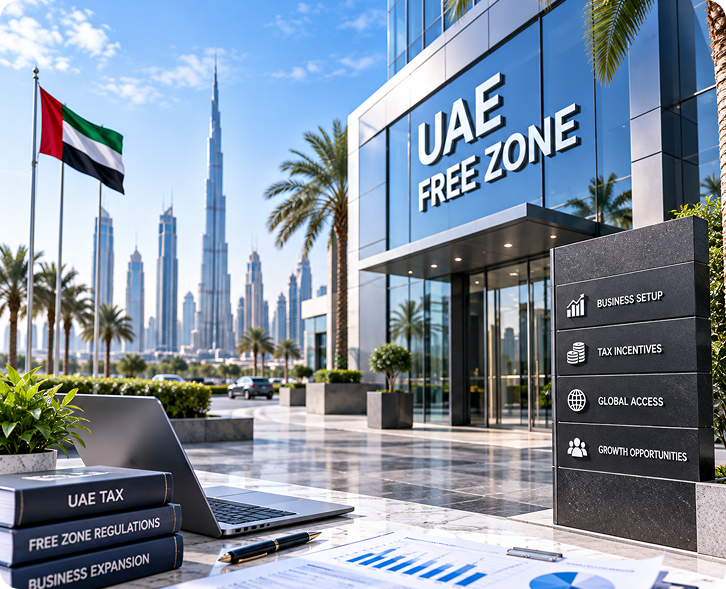
Companies operating in designated Free Zones in the UAE with a valid Qualifying Free Zone Person (QFZP) license benefit from a 0% corporate tax rate on their Qualifying Income. This applies to income from activities carried out within the Free Zone and transactions with other Free Zone Persons.
However, QFZPs lose the 0% benefit on income derived from Excluded Activities or through a Permanent Establishment (PE) outside the Free Zone (mainland UAE or a foreign country). In such cases, the standard 9% corporate tax rate is applicable.
It is advisable to consult the relevant Free Zone authority or a corporate tax consultant in the UAE for detailed information on Free Zone benefits and qualifying activities.
Any business whose financial year begins on or after June 1, 2023, will be subject to corporate tax in the same year. For example, if a company’s financial year starts on August 1, 2023, and ends on July 31, 2024, it will be liable for corporate tax from August 2023, as this marks its first financial year under the CT regime.
Conversely, if a business’s financial year starts on February 1, 2023, it will become subject to corporate tax the following year, i.e., from February 1, 2024, to January 31, 2025.
Our team provides practical, reliable and business-focused corporate tax services to help you stay compliant and make informed decisions for long-term growth.
In-depth tax knowledge
Based on your business needs
Meet all regulatory requirements
A trusted partner for your growth